Real Estate
Mortgage déjà vu
Your home is not an ATM, it’s a long-term investment
The movie ‘The Big Short’ has given us insight into the role of the financial institutions in the housing crash.
Remember back in the early to mid-2000s when interest rates were low, financing was creative and mortgage loans were given out like candy by some unscrupulous lenders?
Properties were appreciating so quickly that homeowners were often encouraged to refinance and use the rising equity in their homes for debt consolidation, home improvements, college tuition and vacations.
Back then, borrowing money was easy. A person could state his income and verify his assets (SIVA loan), state both her income and her assets (SISA loan), or obtain a no income, no asset loan (NINA) just by having a stellar credit rating and paying a higher interest rate.
And remember those adjustable rate mortgages known as “Option ARMs,” where the borrower could choose each month to make a fully amortized payment, an interest-only payment, or an even lower payment based on an initial “teaser” rate? The initial rate was so low that the principal and interest you didn’t pay on a monthly basis would be added to the loan amount and when it came time to pay off the loan, you owed more than you did when you initially got it.
The assumption in the lending community was that rapid appreciation would overtake the additional debt and result in a profit on sale despite your having added to your initial loan amount. Nice work if you can get it and, like a Ponzi scheme, it worked for a while.
A Home Equity Line of Credit (HELOC) was also a popular option. You didn’t need to refinance; just get a new appraisal substantiating a higher value and have an instant line of credit of up to 100 percent of the newly appraised value. Easy peasy.
Then the economy took a downward turn and the money that had flowed so freely dried up. Many homeowners simply put their heads in the sand, refusing to believe that third notice from the mortgage company containing the dreaded word, “foreclosure.”
Years later, I would tell my clients who had to bring additional funds to closing to be able to sell their homes that they did not lose their equity but simply spent it in advance. One could only hope to rob Peter to pay Paul for so long until Peter demanded payment as well.
But sometimes Peter agreed to accept less than owed and the concept of the short sale re-integrated itself into the housing market. It grew so exponentially that our tax laws were changed to eliminate penalties for debt forgiven by financial institutions.
The movie “The Big Short” has given us insight into the role of the financial institutions in the housing crash, but consumers were not entirely blameless. Some most certainly must share responsibility for their own fate by not seeking to understand their loan documents and by being mesmerized by the shiny object before them – a home they knew they could not really afford.
There are still areas of the country where people have not crawled out of the mortgage abyss so imagine my surprise the other day when I heard a television commercial for a lender that used the tag line: “Your home is your bank.”
To quote Yogi Berra, it was “like déjà vu all over again.”
Let me be clear: When I bought my first house, the interest rate was 11.75 percent. I also remember earlier conversations around the dinner table where my parents discussed rates as high as 18-21 percent, so I’m all for creative mortgage loan programs that make homeownership more affordable.
The problem with the home-as-bank theory, however, is that it presupposes that the borrower a) has equity in the home, b) has the income to handle higher payments, and c) understands any terms, conditions and limitations of the loan product.
With interest rates beginning to rise since the election, the promise of a 2.99 percent rate with “no closing costs” may seem enticing but remember, folks, there’s no such thing as that proverbial free lunch. The interest rate will have conditions and those closing costs are hidden in there somewhere, either in the amount of the loan or incorporated into the interest rate.
So, when deciding on a suitable type of mortgage for your purchase or refinance, remember that your home is not an ATM. Think of it instead as your personal sanctuary and a potential long-term investment in your future. Your financial solvency may depend on it.
Valerie M. Blake can be reached at 202-246-8602 or [email protected]. Each Keller Williams Realty office is independently owned and operated. Equal Housing Opportunity.

Real Estate
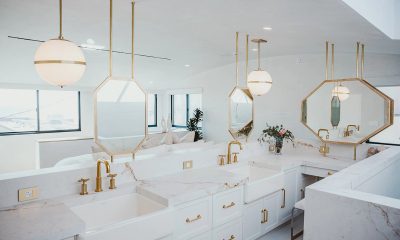
Factors to consider when hiring an interior designer
It’s essential to have confidence in the professionals you engage
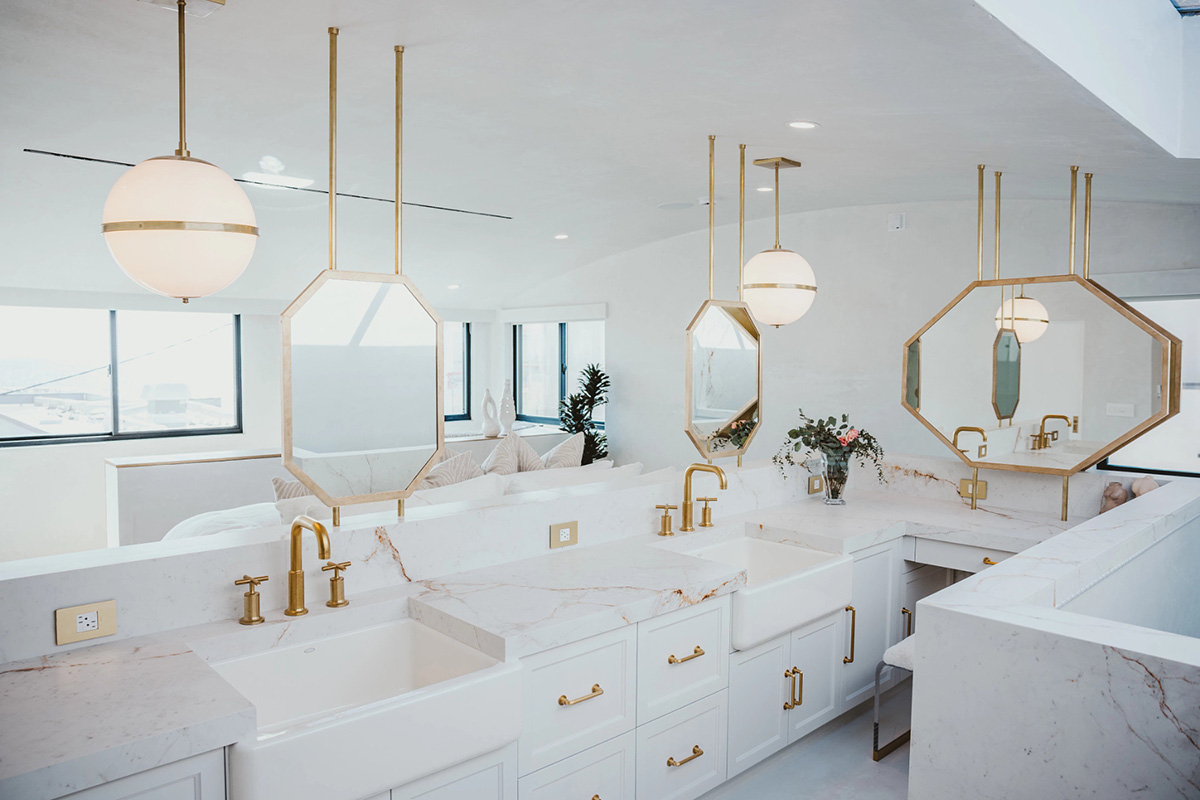
(StatePoint) Ready to redesign your home? Whether you have only a vague notion of how you want your spaces to look or a very specific vision, relying on the expertise of a professional can help you bring your dream home to life. Before choosing and hiring an interior designer, though, be sure to take the following factors into consideration:
Style: Identify your style. Is it boho chic? Industrial? Maximalist? Many designers have their own signature look and preferences. It’s best to understand what vibe you want first, then search for a designer who aligns with that style.
Past client projects: One of the best ways to know whether a particular designer is the right fit for you is to review their past client projects. Ask to see their portfolio or review their finished projects on their website or socials. Also, take a look at reviews and testimonials to ensure their previous customers walked away satisfied with a job well done.
Budget: Communicate your budget in advance of work to confirm that you and your designer are on the same page financially. Your decorator will need this ballpark figure to get a handle on the scope of the project and to make design decisions accordingly. You should also use this conversation to understand their rates so you can decide whether you want to move forward.
Preferred vendors: It’s important that the interior designer you choose has preferred vendors that they work with. These are partners they’ve built strong relationships with that provide the same first-rate experience they do, and have streamlined processes in place. “A home renovation has so many moving parts. That’s why we try to take the hassle out of the process for designers and homeowners alike,” says Katie Zess, senior marketing manager and director of Renewal by Andersen’s Interior Designer Loyalty Program.
Through the loyalty program, the full-service window and door replacement division of Andersen Corporation offers their program members exclusive access and rewards, including a “designer discount” they can share with their clients. Renewal by Andersen also offers designers a dedicated point of contact to ensure a smooth process that’s customized for your project from start to finish. To learn more, visit renewalbyandersen.com.
Before you begin your home renovation, it’s essential to have confidence in the professionals you hire. Be sure your interior designer has fostered partnerships that will streamline your redesign, and that their goals and budget aligns with yours.
Real Estate
The LGBTQ real estate map is being redrawn
Affordability, higher mortgage rates reshaping where we choose to call home
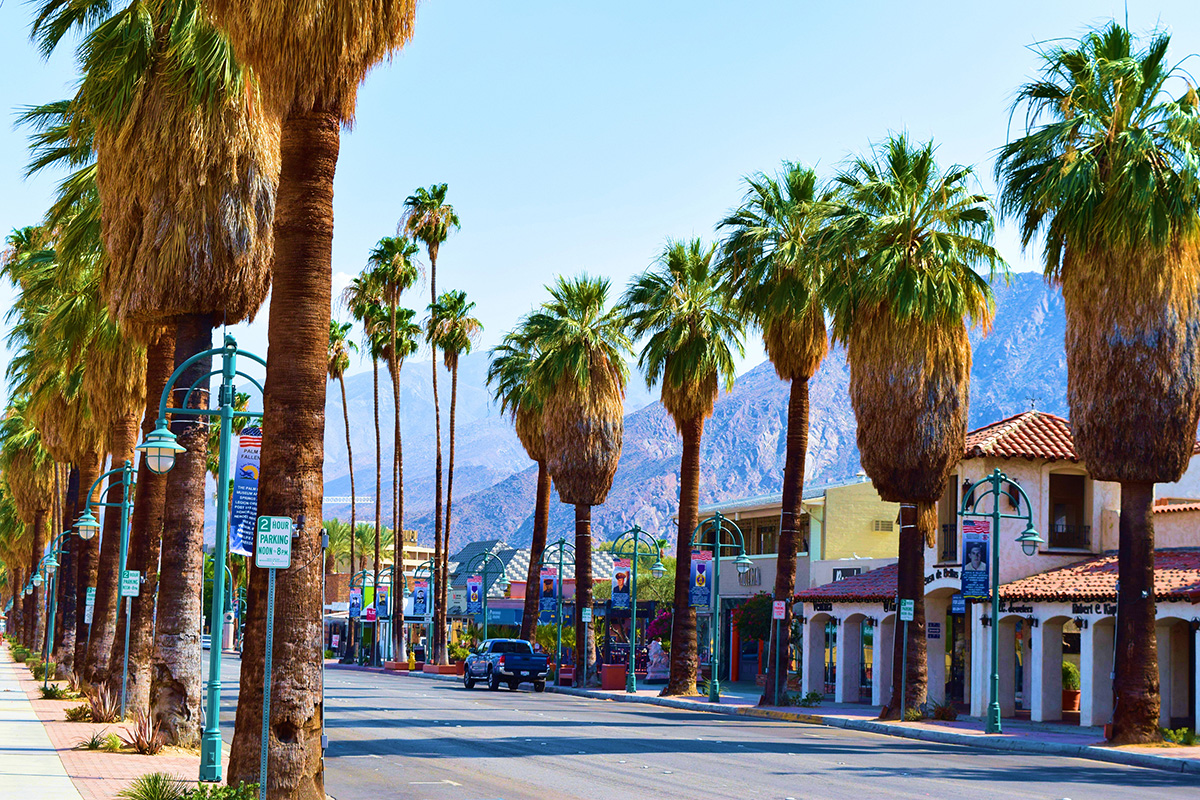
For decades, the map of LGBTQ+ America was relatively easy to recognize.
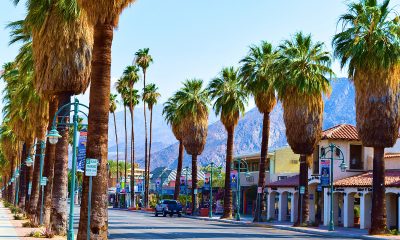
New York. San Francisco. Los Angeles. Palm Springs. Provincetown. Fort Lauderdale and Wilton Manors.
These communities became LGBTQ+ destinations because they offered something that wasn’t always easy to find elsewhere: visibility, acceptance, community and the freedom to live openly.
But that map is changing.
Today’s LGBTQ+ homebuyers are navigating a housing market defined by high prices, elevated mortgage rates and affordability challenges. At the same time, remote and hybrid work, retirement and the growth of LGBTQ+ communities beyond traditional destinations are giving buyers more choices about where to live.
Increasingly, the question isn’t simply, “Where are the most LGBTQ-friendly places to live?”
It’s also: “Where can I find community and afford the life I want?”
That shift may become one of the defining LGBTQ+ real estate trends of the coming decade.
Affordability Is Changing the Conversation
For many buyers, the biggest issue in today’s housing market is simple: the monthly payment.
The average 30-year fixed mortgage rate was 6.95% in mid-September, compared with 6.26% a year earlier, according to Freddie Mac.
Meanwhile, the median price of an existing U.S. home reached $429,100 in August, according to the National Association of Realtors.
The combination of elevated home prices and higher borrowing costs has changed what many Americans can afford—and where they can afford it.
Some buyers are purchasing smaller homes or condominiums. Others are moving farther from major urban centers. Still others are reconsidering expensive markets entirely.
For LGBTQ+ buyers, this is helping broaden the definition of an LGBTQ+-friendly place to call home.
LGBTQ+ Buyers Have More Choices
A generation ago, relocating away from a major city or established gay neighborhood could sometimes mean sacrificing access to a visible LGBTQ+ community.
That’s increasingly less true.
Traditional LGBTQ+ destinations such as Palm Springs, Fort Lauderdale and Wilton Manors, San Francisco, New York and Provincetown remain important centers of LGBTQ+ life. But today, LGBTQ+ buyers can also find established or growing communities in cities across the country.
Places such as Minneapolis, Columbus, Pittsburgh, Richmond, Atlanta and the Tampa Bay area are among the markets attracting buyers who may be looking for a different balance of housing costs, lifestyle and community.
The goal isn’t necessarily to find the cheapest house.
It’s to find the right combination of affordability, LGBTQ+ community, lifestyle, employment opportunities, healthcare, culture and quality of life.
Remote and hybrid work have expanded those possibilities for some buyers. If a job no longer requires being in an expensive employment center five days a week, the geographic search for a home can become considerably larger.
That can make communities that once seemed impractical suddenly worth considering.
Retirement Is Redrawing the Map, Too
Retirement is another important part of the changing LGBTQ+ real estate landscape.
As more Americans reach retirement age, LGBTQ+ retirees are considering where they want to spend the next chapter of their lives. Housing costs, taxes, healthcare, climate and proximity to airports, restaurants and cultural activities all play a role.
But LGBTQ+ retirees may have additional questions.
Will I feel comfortable living openly?
Is there an LGBTQ+ community nearby?
Can I find LGBTQ+-affirming healthcare?
Will I have opportunities to build a social network as I get older?
Those considerations can make choosing a retirement destination particularly personal.
Palm Springs and Fort Lauderdale/Wilton Manors remain well-known LGBTQ+ retirement destinations. But retirees are also exploring smaller cities and communities across the Southeast, Midwest and other regions where housing costs and lifestyles can look very different.
For many, the search is becoming less about moving to a famous gay destination and more about finding a place where community, lifestyle and affordability intersect.
Buyers Finally Have More Leverage
There is another significant change in today’s housing market: buyers have regained some negotiating power.
The National Association of Realtors reported 1.62 million existing homes for sale in August, up 5.9% from a year earlier. That represents approximately 4.9 months of housing supply, the highest level in more than a decade.
Realtor.com also reported that 20.4% of active listings had experienced a price reduction in August.
That’s a very different environment from the pandemic-era housing market, when buyers in many communities faced bidding wars, waived inspections and offers well above asking price.
Depending on the market, today’s buyer may have more time to evaluate a property and greater opportunity to negotiate price, repairs, closing costs or other concessions.
But there is an important caveat: there is no single national housing market.
Conditions can vary dramatically from one city—or even one neighborhood—to another. Some markets remain competitive, while others have considerably more inventory and negotiating room.
That’s one reason local expertise matters.
Sellers Need a Different Strategy
The changing market also has implications for LGBTQ+ homeowners considering selling.
Strategies that worked several years ago may not work today.
Buyers are highly sensitive to monthly payments, and an overpriced home can quickly be passed over when competing properties are available.
Sellers should pay close attention not only to recent comparable sales but also to homes currently competing for the same buyer.
Condition matters, too.
Repairs, landscaping, staging and professional photography can make a meaningful difference when buyers have more choices. Pricing correctly from the beginning has also become increasingly important.
More Than 30 Years Serving the LGBTQ+ Community
One part of buying or selling a home hasn’t changed: the importance of working with a real estate professional who understands your priorities.
For more than 30 years, GayRealEstate.com has served the LGBTQ+ community, connecting buyers and sellers with LGBTQ+ and allied real estate professionals throughout the United States.
Over that time, the GayRealEstate.com network has supported more than $2 billion in real estate sales and more than 55,000 transactions.
Behind those numbers are thousands of people making one of life’s most personal decisions: where to call home.
For LGBTQ+ buyers, that conversation can involve much more than bedrooms, bathrooms and price per square foot. It can include community, acceptance, healthcare, family, retirement, lifestyle and the ability to live openly.
An experienced LGBTQ+ or allied real estate professional can understand why those considerations belong in the real estate conversation.
Finding Home in a Changing America
The 2026 housing market presents real challenges.
Mortgage rates remain elevated. Home prices are high. Affordability continues to strain buyers across much of the country.
But there are also signs of a more balanced market. Inventory has increased. Price reductions have become more common. Buyers in many markets have regained negotiating power.
And for LGBTQ+ Americans, something else has changed: there are more places to consider calling home.
The next great LGBTQ+ destination doesn’t necessarily need the country’s largest Pride celebration or its most famous gay neighborhood.
It could be a smaller city with a growing LGBTQ+ community, attainable housing, good healthcare, strong cultural amenities and a quality of life that leaves room for travel, retirement or simply enjoying the home you’ve worked hard to own.
Ultimately, today’s LGBTQ+ real estate search increasingly comes down to three questions:
Where can I afford the life I want?
Where will I find my community?
And where will I feel at home?
The answers are becoming more varied—and that’s helping redraw the map of LGBTQ+ America.
Scott Helms is with GayRealEstate.com.
GayRealEstate.com has served the LGBTQ+ community for more than 30 years, connecting LGBTQ+ homebuyers and sellers with LGBTQ+ and allied real estate professionals across the United States. Its network has supported more than $2 billion in real estate sales and more than 55,000 transactions.
One of the biggest headaches of the new home process is the actual moving part. By the time someone is buying a home, most people are beyond the “I just need a pickup truck, a pizza and a case of beer for my friends.”
If that is still someone’s preferred way to move, that’s great. However, many people find they need a much more robust plan. It can also trigger a lot of feelings about items one owns, what to do with them, do they have too much, should I keep this memento that I never use? Etc.
Moving is a chance for a person to “clean house” literally, figuratively, spiritually and energetically. A person can figure out which items they want to keep, and which need to go. As someone who recently moved across the country, I can speak to this experience. It’s also time for what people call “the fresh start effect.” This phenomenon, according to psychologists, can happen in little moments (like the start of a new work week) and bigger moments (such as moving from one home to the next).
The fresh start effect offers these benefits often mentioned by psychologists:
- Mental Accounting: Dates act as chapter breaks, letting you put past failures into a previous period.
- Psychological Distance: You separate your flawed past self from your aspirational future self (“That was the old me”).
- Optimism Boost: New beginnings clear mental clutter and increase your sense of agency and control
Does this mean that “the new you” will be the perfect version you envisioned? Probably not. We are humans. But it might mean you get a chance to “leave some of the old you behind” within the walls you used to live in, and now have a chance to have a new layout, a new décor, a new color pattern, new wallpaper, donate old furniture and books or magazines, throw out clothes you no longer use or fit in, and enjoy the opportunity to literally use the, “Does this spark joy?” method that was made so popular by Marie Kondo in her Netflix series.
So, for all its hassle and headache, moving is a chance to shake off the “old you” and try on the new you, to incorporate the items you would like to keep and use more of, and shed the items, habits, and ways of thinking that you feel no longer serve you.
I can speak to the experiences that several of my clients had when they moved from a previous residence to a newer one. It usually coincided with a change in relationship status, a change in employment, a change in family size, but sometimes it just seemed to correlate to a new attitude and perspective that the client was really hoping for.
I have literally had clients come to me after the fact, in tears, that they were so happy they made the decision to move out of a situation that no longer served them, and move into one that felt like a much better fit.
Change can be annoying and overwhelming at times, but usually most people come out the other side, not wanting to return to the way they were before.
Joseph Hudson is a referral agent with RLAH. Reach him at 703-587-0597 or [email protected].

Baltimore’s oldest gay bar to reopen this week

Dr. Fauci ‘honored to be part of’ LGBTQ history

Factors to consider when hiring an interior designer

PHOTOS: HRC National Dinner

The LGBTQ real estate map is being redrawn

Washington Blade responds to concerns over White House pool duties

Caso Karlina: Una sentencia histórica contra las terapias de «conversión»

Clavicular charged in alleged rape of teenage influencer

Young people should know history of the fight for human rights

Dutch prime minister visits Stonewall Inn
-

 Commentary5 days ago
Washington Blade responds to concerns over White House pool duties
-
Online Culture5 days ago
Clavicular charged in alleged rape of teenage influencer
-
Ecuador5 days ago
Caso Karlina: Una sentencia histórica contra las terapias de «conversión»
-
Opinions5 days ago
Young people should know history of the fight for human rights