Living
Housing market stays strong in D.C.
There’s good news and bad news in real estate these days, but if you’re in the immediate area around Washington, the news is mostly good.
The Case-Shiller Index, published by Standard & Poor’s and considered the most accurate report of home values both across the country and within 20 major metropolitan regions, showed Washington to be the strongest market in the U.S., with values increasing 3 percent from March to April and up 4 percent from April of last year. And, while values nationwide are down nearly 4 percent compared to April of last year, they were up from March .7 percent.
Thirteen of the 20 city areas tracked increased in value from last year (compared to only one — Washington — that had increased values as of the last report in December), but six areas showed the lowest values in four years, including Chicago, Miami, Tampa, Detroit, Las Vegas and Charlotte, N.C.
What does all this mean? It’s clearly a difficult fortune to read for the country as a whole, but as a D.C. Realtor, I can only see an optimistic outlook for our region. The combination here of a high median income, relatively low unemployment and a well-educated population makes for a strong market and will continue to do so in the future.
Also contributing to my rosy outlook on home values is the local data regarding the inventory of available housing, specifically the lack thereof. Delta Associates, an Alexandria firm that tracks new condominium inventory and new construction, reported that the inventory of upcoming and available new condominiums is only 3,629 units for the entire region, which is down from nearly 20,000 in 2007.
This drop of more than 80 percent has had, and will continue to have, a major impact on prices, as the simple laws of supply and demand dictate. To wit, while new condo prices for the metro-D.C. region dipped 2.4 percent since last year, Washington and Montgomery County saw increases of 1.8 and .8 percent, respectively. Inventory of resale housing is generally extremely low as well, to the bane of agents and buyers alike. In fact, I have personally had to negotiate multiple-offer situations in three of my last four transactions due to the low supply of and high demand for quality product.
One bit of bad news for all of us Washingtonians is the upcoming reduction in the loan limits that will be backed by the federal government. Since 2008, we have benefited from a temporary loan limit increase to $729,750 for loans that are guaranteed by Fannie Mae, Freddie Mac and the Federal Housing Administration (FHA). In October, if Congress does not act to stop it, the limit will drop back to $625,500.
Many buyers, sellers and lenders are scrambling to act before the limit drops and many are fearful that due to the high cost of housing in the area, the limit decreases will have profound effects, especially on upper-end purchases. My hunch, however, is that it will impact only those purchases for which the extra $100,000 or so would have helped to get the loan to begin with. Purchases costing a million or more would require more than 25 percent down to get a government-backed loan, which is more than enough to qualify buyers for non-conforming (as in non-government-backed) loans with great rates anyway.
It’s only going to be the properties priced between $650,000 and $755,000 (roughly the loan limit plus the lowest downpayment possible of 3.5 percent) that will suffer and only those may have problems selling if the buyers available literally have no more than the very lowest downpayment required. That said, if you are a buyer in that price range and wish to put down a low downpayment, or if you’re a seller with a house in that range, you may wish to list before those limits take effect to ensure you have the most options, whether it’s options for houses you could afford or buyers who could afford your house.
To put a bit of icing on this bittersweet cake, I am pleased to report that interest rates continue to rest at truly unbelievable values, with 30-year fixed rates as low as 4 percent with no points (for a superconforming loan, nonetheless!) in the past month.
My clients are thrilled at the rates they’ve been offered recently, and when rates stay low, property values stay high. There are also a number of new loan programs available that offer even lower rates (some in the high twos) with a moderate level of risk with so-called “5/5 ARMs,” or adjustable rate mortgages that have reasonable increase limits, lifetime caps and only change once every five years, eliminating some anxiety about a yearly hike.
All in all, it’s great to be a Washingtonian these days, and not just for the amazing view of fireworks on the fourth of July.
David Bediz is a Realtor at Coldwell Banker Residential Brokerage and a Principal of the Dwight and David Real Estate Group. He can be reached at 202-352-8456 or through DwightandDavid.com.
Real Estate
The financial realities facing LGBTQ+ first-time buyers
Beyond affordability: credit, support systems, and trust
For many first-time buyers, the conversation starts with affordability: home prices, interest rates, monthly payments, and the down payment. Yet these initial figures represent only part of the picture. For LGBTQ+ first-time buyers, credit history, access to financial support, household structure, and whether the professionals involved feel trustworthy can also shape the path to homeownership. While these hurdles affect various demographics and show up differently for everyone, they often create friction long before an offer is submitted.
Affordability Is Only the First Filter
A buyer may be able to handle a monthly mortgage payment and still struggle to qualify for the loan they expected. Loan approval hinges on a holistic review that goes far beyond basic income. Lenders generally consider credit history, debt obligations, available cash, employment and income documentation, and the buyer’s overall financial profile. That distinction matters for first-time buyers who have spent years paying rent successfully but have a limited credit file, uneven credit history, student loan balances, or other debt. Even renters with flawless track records of managing monthly payments can run into unexpected hurdles when a lender applies standard underwriting criteria. Early preparation can help. By auditing credit reports, resolving discrepancies, tackling existing debt, accumulating savings, and engaging early with a certified loan officer, buyers can catch and fix vulnerabilities before they derail a deal.
Support Systems Can Change What Is Possible
Homebuying advice often assumes that first-time buyers have access to a familiar financial safety net: parents who can help with a down payment, relatives who can provide a gift, or family members who can explain the process because they have purchased homes before. That support is not universal. Some LGBTQ+ buyers have strong financial and emotional support from their families of origin. Others turn to partners, close friends, trusted mentors, or chosen family for backing, while some navigate the entire venture independently. The important point is not to assume what a buyer’s support system looks like. The difference can be practical. When family assistance isn’t an option, buyers often need more time to build reserves. They may rely heavily on down-payment assistance programs or specialized loan options offered by their lender. A buyer receiving gift funds may need to understand documentation requirements before using those funds. Support also includes knowledge. Those raised around property owners often enter the process with a baseline understanding of key mechanics like earnest money, home inspections, appraisals, closing fees, and mortgage terminology. A first-generation buyer may be learning it all at once. Lacking that foundational awareness can lead to costly mistakes surrounding critical deadlines, hidden fees, and contractual obligations.
Household Structure Deserves Careful Planning
LGBTQ+ buyers may purchase alone, with a spouse, with an unmarried partner, or in another shared household arrangement. These varying arrangements change the game for mortgage applications, combined credit assessments, titling methods, and the division of ongoing home equity. Those decisions deserve deliberate attention. Because two co-buyers may have vastly different credit standings, putting both names on a mortgage application isn’t always the best route. Mortgage responsibility and legal ownership are related, but not identical. A first-time buyer should be able to ask these questions without feeling awkward about explaining a relationship, correcting assumptions, or wondering whether a professional understands the household in front of them. If legal or tax complications surface, buyers should seek tailored advice from an independent professional.
Trust Is a Financial Issue, Too
Trust can sound like a “soft” consideration compared with a credit score or closing-cost estimate. In reality, it directly shapes strategic financial choices at every stage of the transaction. A buyer who doesn’t feel comfortable with an agent or lender may hesitate to disclose concerns, ask basic questions, or admit they don’t understand a term. They might hold back on detailing how they plan to co-own a home with a partner, or unquestioningly agree to costs without fully grasping the long-term impact. That is a poor foundation for a major financial commitment. First-time buyers need professionals who explain the process clearly, respect the buyer’s household and identity, and make room for questions without judgment. High-level skill and deep market knowledge remain essential, but clear communication and accountability are equally vital. Buyers should understand who each professional represents, what that professional is responsible for, and when outside legal, tax, insurance, or financial advice may be appropriate.
A Better First Step Is Better Information
The financial realities of buying a first home extend well beyond the list price. A buyer’s credit profile determines loan availability, while their support network dictates their financial wiggle room and access to guidance. Household structure can affect borrowing and ownership decisions. Ultimately, trust is what empowers a buyer to speak up, ask tough questions, and safeguard their financial well-being. For LGBTQ+ buyers, an affirming experience should not replace professional expertise. True support requires both identity-affirming care and top-tier professional guidance working in tandem. Pride Real Estate Connections was built from lived experience with exclusion in real estate and connects LGBTQ+ buyers, sellers, families, and allies with independent real estate professionals through its referral network. The goal is simple: connect clients with vetted agents and lenders who offer unconditional respect, deep expertise, and a space where no one has to minimize who they are. Buying a first home is already complex. Buyers deserve the clarity to focus on core choices: managing their budget, structuring ownership, navigating tradeoffs, and relying on advisors who truly have their back. Pride REC is a referral and connection platform, not a brokerage, and independent real estate professionals provide their own services. Buyers must execute their own due diligence and partner with accredited legal, tax, and lending specialists tailored to their unique needs.
Devin Schaff is co-founder of Pride Real Estate Connections.
Real Estate
Factors to consider when hiring an interior designer
It’s essential to have confidence in the professionals you engage
(StatePoint) Ready to redesign your home? Whether you have only a vague notion of how you want your spaces to look or a very specific vision, relying on the expertise of a professional can help you bring your dream home to life. Before choosing and hiring an interior designer, though, be sure to take the following factors into consideration:
Style: Identify your style. Is it boho chic? Industrial? Maximalist? Many designers have their own signature look and preferences. It’s best to understand what vibe you want first, then search for a designer who aligns with that style.
Past client projects: One of the best ways to know whether a particular designer is the right fit for you is to review their past client projects. Ask to see their portfolio or review their finished projects on their website or socials. Also, take a look at reviews and testimonials to ensure their previous customers walked away satisfied with a job well done.
Budget: Communicate your budget in advance of work to confirm that you and your designer are on the same page financially. Your decorator will need this ballpark figure to get a handle on the scope of the project and to make design decisions accordingly. You should also use this conversation to understand their rates so you can decide whether you want to move forward.
Preferred vendors: It’s important that the interior designer you choose has preferred vendors that they work with. These are partners they’ve built strong relationships with that provide the same first-rate experience they do, and have streamlined processes in place. “A home renovation has so many moving parts. That’s why we try to take the hassle out of the process for designers and homeowners alike,” says Katie Zess, senior marketing manager and director of Renewal by Andersen’s Interior Designer Loyalty Program.
Through the loyalty program, the full-service window and door replacement division of Andersen Corporation offers their program members exclusive access and rewards, including a “designer discount” they can share with their clients. Renewal by Andersen also offers designers a dedicated point of contact to ensure a smooth process that’s customized for your project from start to finish. To learn more, visit renewalbyandersen.com.
Before you begin your home renovation, it’s essential to have confidence in the professionals you hire. Be sure your interior designer has fostered partnerships that will streamline your redesign, and that their goals and budget aligns with yours.
Real Estate
The LGBTQ real estate map is being redrawn
Affordability, higher mortgage rates reshaping where we choose to call home
For decades, the map of LGBTQ+ America was relatively easy to recognize.
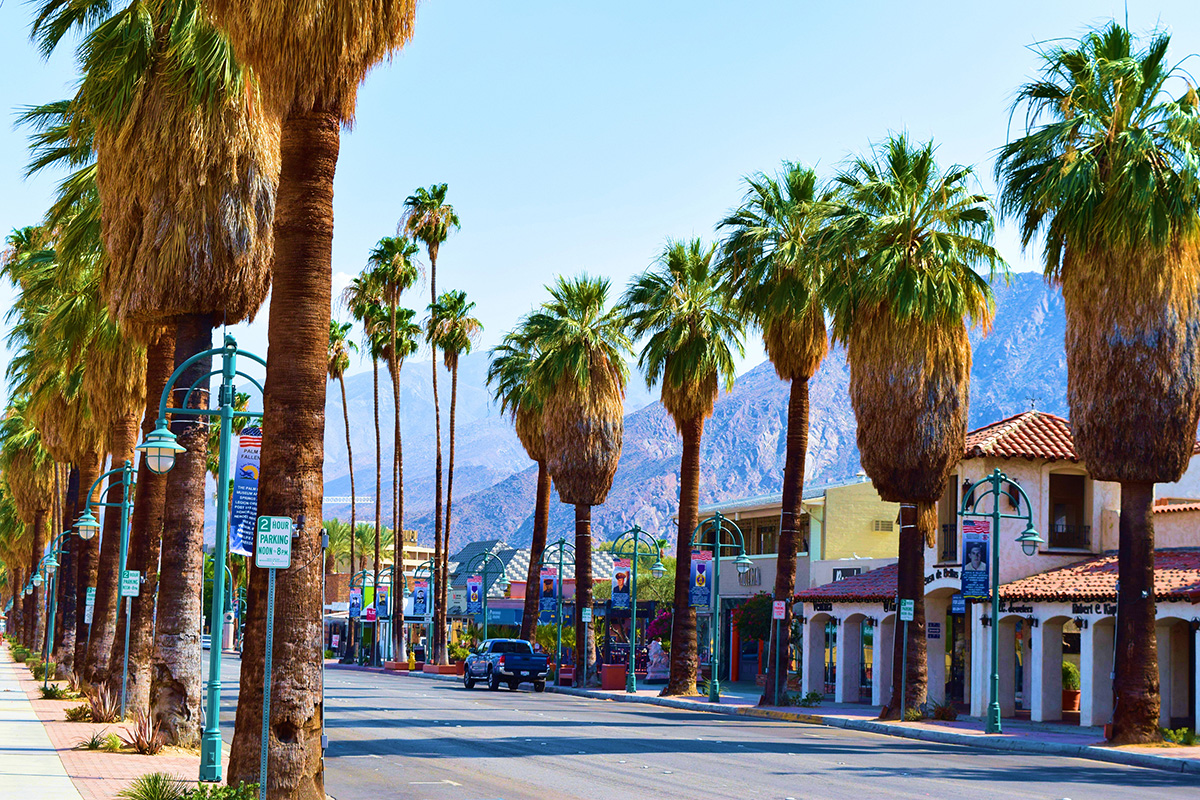
New York. San Francisco. Los Angeles. Palm Springs. Provincetown. Fort Lauderdale and Wilton Manors.
These communities became LGBTQ+ destinations because they offered something that wasn’t always easy to find elsewhere: visibility, acceptance, community and the freedom to live openly.
But that map is changing.
Today’s LGBTQ+ homebuyers are navigating a housing market defined by high prices, elevated mortgage rates and affordability challenges. At the same time, remote and hybrid work, retirement and the growth of LGBTQ+ communities beyond traditional destinations are giving buyers more choices about where to live.
Increasingly, the question isn’t simply, “Where are the most LGBTQ-friendly places to live?”
It’s also: “Where can I find community and afford the life I want?”
That shift may become one of the defining LGBTQ+ real estate trends of the coming decade.
Affordability Is Changing the Conversation
For many buyers, the biggest issue in today’s housing market is simple: the monthly payment.
The average 30-year fixed mortgage rate was 6.95% in mid-September, compared with 6.26% a year earlier, according to Freddie Mac.
Meanwhile, the median price of an existing U.S. home reached $429,100 in August, according to the National Association of Realtors.
The combination of elevated home prices and higher borrowing costs has changed what many Americans can afford—and where they can afford it.
Some buyers are purchasing smaller homes or condominiums. Others are moving farther from major urban centers. Still others are reconsidering expensive markets entirely.
For LGBTQ+ buyers, this is helping broaden the definition of an LGBTQ+-friendly place to call home.
LGBTQ+ Buyers Have More Choices
A generation ago, relocating away from a major city or established gay neighborhood could sometimes mean sacrificing access to a visible LGBTQ+ community.
That’s increasingly less true.
Traditional LGBTQ+ destinations such as Palm Springs, Fort Lauderdale and Wilton Manors, San Francisco, New York and Provincetown remain important centers of LGBTQ+ life. But today, LGBTQ+ buyers can also find established or growing communities in cities across the country.
Places such as Minneapolis, Columbus, Pittsburgh, Richmond, Atlanta and the Tampa Bay area are among the markets attracting buyers who may be looking for a different balance of housing costs, lifestyle and community.
The goal isn’t necessarily to find the cheapest house.
It’s to find the right combination of affordability, LGBTQ+ community, lifestyle, employment opportunities, healthcare, culture and quality of life.
Remote and hybrid work have expanded those possibilities for some buyers. If a job no longer requires being in an expensive employment center five days a week, the geographic search for a home can become considerably larger.
That can make communities that once seemed impractical suddenly worth considering.
Retirement Is Redrawing the Map, Too
Retirement is another important part of the changing LGBTQ+ real estate landscape.
As more Americans reach retirement age, LGBTQ+ retirees are considering where they want to spend the next chapter of their lives. Housing costs, taxes, healthcare, climate and proximity to airports, restaurants and cultural activities all play a role.
But LGBTQ+ retirees may have additional questions.
Will I feel comfortable living openly?
Is there an LGBTQ+ community nearby?
Can I find LGBTQ+-affirming healthcare?
Will I have opportunities to build a social network as I get older?
Those considerations can make choosing a retirement destination particularly personal.
Palm Springs and Fort Lauderdale/Wilton Manors remain well-known LGBTQ+ retirement destinations. But retirees are also exploring smaller cities and communities across the Southeast, Midwest and other regions where housing costs and lifestyles can look very different.
For many, the search is becoming less about moving to a famous gay destination and more about finding a place where community, lifestyle and affordability intersect.
Buyers Finally Have More Leverage
There is another significant change in today’s housing market: buyers have regained some negotiating power.
The National Association of Realtors reported 1.62 million existing homes for sale in August, up 5.9% from a year earlier. That represents approximately 4.9 months of housing supply, the highest level in more than a decade.
Realtor.com also reported that 20.4% of active listings had experienced a price reduction in August.
That’s a very different environment from the pandemic-era housing market, when buyers in many communities faced bidding wars, waived inspections and offers well above asking price.
Depending on the market, today’s buyer may have more time to evaluate a property and greater opportunity to negotiate price, repairs, closing costs or other concessions.
But there is an important caveat: there is no single national housing market.
Conditions can vary dramatically from one city—or even one neighborhood—to another. Some markets remain competitive, while others have considerably more inventory and negotiating room.
That’s one reason local expertise matters.
Sellers Need a Different Strategy
The changing market also has implications for LGBTQ+ homeowners considering selling.
Strategies that worked several years ago may not work today.
Buyers are highly sensitive to monthly payments, and an overpriced home can quickly be passed over when competing properties are available.
Sellers should pay close attention not only to recent comparable sales but also to homes currently competing for the same buyer.
Condition matters, too.
Repairs, landscaping, staging and professional photography can make a meaningful difference when buyers have more choices. Pricing correctly from the beginning has also become increasingly important.
More Than 30 Years Serving the LGBTQ+ Community
One part of buying or selling a home hasn’t changed: the importance of working with a real estate professional who understands your priorities.
For more than 30 years, GayRealEstate.com has served the LGBTQ+ community, connecting buyers and sellers with LGBTQ+ and allied real estate professionals throughout the United States.
Over that time, the GayRealEstate.com network has supported more than $2 billion in real estate sales and more than 55,000 transactions.
Behind those numbers are thousands of people making one of life’s most personal decisions: where to call home.
For LGBTQ+ buyers, that conversation can involve much more than bedrooms, bathrooms and price per square foot. It can include community, acceptance, healthcare, family, retirement, lifestyle and the ability to live openly.
An experienced LGBTQ+ or allied real estate professional can understand why those considerations belong in the real estate conversation.
Finding Home in a Changing America
The 2026 housing market presents real challenges.
Mortgage rates remain elevated. Home prices are high. Affordability continues to strain buyers across much of the country.
But there are also signs of a more balanced market. Inventory has increased. Price reductions have become more common. Buyers in many markets have regained negotiating power.
And for LGBTQ+ Americans, something else has changed: there are more places to consider calling home.
The next great LGBTQ+ destination doesn’t necessarily need the country’s largest Pride celebration or its most famous gay neighborhood.
It could be a smaller city with a growing LGBTQ+ community, attainable housing, good healthcare, strong cultural amenities and a quality of life that leaves room for travel, retirement or simply enjoying the home you’ve worked hard to own.
Ultimately, today’s LGBTQ+ real estate search increasingly comes down to three questions:
Where can I afford the life I want?
Where will I find my community?
And where will I feel at home?
The answers are becoming more varied—and that’s helping redraw the map of LGBTQ+ America.
Scott Helms is with GayRealEstate.com.
GayRealEstate.com has served the LGBTQ+ community for more than 30 years, connecting LGBTQ+ homebuyers and sellers with LGBTQ+ and allied real estate professionals across the United States. Its network has supported more than $2 billion in real estate sales and more than 55,000 transactions.

Bet Mishpachah participates in D.C. Oct. 7 commemoration ceremony

Man charged in Mall of America shooting plot inspired by Pulse massacre: report

Bar Betsie, inviting and intimate, marks one-year anniversary

Trump, Netanyahu, and Putin are all war criminals

Center Arts Gallery celebrates 10 years with reception, auction

Eliot Glazer’s new book an engaging collection of essays

Equality Chamber hosts Pride in Business Expo and Profits & Pours

Learn more about Virginia’s queer history

The financial realities facing LGBTQ+ first-time buyers

Lula, Flávio Bolsonaro to face off in second round of Brazilian presidential election
-

 Books5 days ago
Eliot Glazer’s new book an engaging collection of essays
-
Out & About5 days ago
Equality Chamber hosts Pride in Business Expo and Profits & Pours
-
Out & About5 days ago
Learn more about Virginia’s queer history
-
Real Estate5 days ago
The financial realities facing LGBTQ+ first-time buyers