Real Estate
What can buyers do to combat rising interest rates?
A fine line between inflation, control, and recession
During the past quarter, we have seen most favored interest rates rise from 3.5% to 4.5%. While these rates are still historically among the lowest in decades, that fact may not make you feel any better about the possibility of paying more for your first or next home.
This week’s rate is the highest we have seen in two-and-a-half years. Loan officers are projecting further increases in rates as the Federal Reserve (the “Fed”) attempts to control inflation. Basic economics tells us that more expensive credit slows spending, which, in turn, lowers prices. It can be a fine line to walk between inflation, control, and recession.
People who are seeking a conventional loan of $647,200 or less with a 20% down payment will likely receive the best 30-year fixed rate if they hold a salaried job and have a credit score of more than 740.
Using an example of a typical $750,000 D.C. rowhouse with a $150,000 down payment, the difference between the principal and interest payment at 3.5% and 4.5% is $346 a month without taking tax-deductible mortgage interest into consideration.
Often, there is a rate premium paid for the purchase of a condominium or cooperative apartment, for being self-employed, for less than stellar credit, and for lower down payments or larger loans.
So, what can you do to minimize the effects of an increase in interest rates?
First, make sure your credit is squeaky clean. Consult a loan officer to get a copy of your tri-merged credit report (Equifax, Experian, and Trans Union) to avoid any surprises. Do not start paying off debt or closing credit cards without your loan officer’s input. There is such a thing as good debt where credit is concerned.
Shop around for your mortgage and consider alternative mortgage programs. For example, as rates rise, adjustable mortgages with payments fixed for 5, 7, or 10 years can be more affordable. A 30-year fixed rate, often thought to be the safest bet, may not be as desirable if you will not be keeping the home for 30 years.
Search for any special benefits for which you may qualify. D.C., Maryland, and Virginia all have programs geared toward people with low to moderate incomes or who have as little as 3% for a down payment. The funds for these programs may have been secured when rates were lower, with savings passed along to the consumer.
This should be the time to look for sellers who have assumable FHA mortgages obtained when rates were lower. In addition to lower rates, the cost of assuming such a mortgage will be less than originating a new one, so you might save money in closing costs as well. VA loans can also be assumed by active-duty military or veterans, or by others under certain circumstances.
Have the lender you choose provide you with an estimate of what your mortgage payment may be at different rates. Even if you can afford the payment, it is best not to be surprised as you go through the process. When you find a rate that gives you a comfortable monthly payment, lock it in so your rate will not go up if or when the Fed makes another adjustment.
Consider whether to pay points to lower your interest rate. One point is equal to one percent of the loan amount, but you can “buy down” the rate in increments of as little as 1/8 of a percent. When interest rates were higher than 10%, it was quite common for sellers to pay points to help a buyer afford his loan. While I do not anticipate this happening here anytime soon, the “buy down” procedure still exists.
Find an infusion of cash to lower your loan amount. The National Bank of Mom and Dad is a common place to obtain a gift of funds. In 2022, each parent can give a gift of $16,000 to a child or grandchild without tax consequences to the giver or the recipient. Consult your tax adviser for more information.
If you have a 401k retirement plan with your employer or a federal government Thrift Savings Plan, you can borrow from it without incurring penalties and pay yourself back with interest. Most lenders will not count this against your debt load.
Lastly, you may need to adjust your expectations regarding size and location of your prospective home, since any increase in rates will affect everything from entry-level condos to luxury properties. Still, with the Fed anticipating raising rates in small increments through 2023, this may still be the optimum time to buy.
Valerie M. Blake is a licensed Associate Broker in D.C., Maryland, and Virginia with RLAH Real Estate. Call or text her at 202-246-8602, email her via DCHomeQuest.com, or follow her on Facebook at TheRealst8ofAffairs.



One of the biggest headaches of the new home process is the actual moving part. By the time someone is buying a home, most people are beyond the “I just need a pickup truck, a pizza and a case of beer for my friends.”
If that is still someone’s preferred way to move, that’s great. However, many people find they need a much more robust plan. It can also trigger a lot of feelings about items one owns, what to do with them, do they have too much, should I keep this memento that I never use? Etc.
Moving is a chance for a person to “clean house” literally, figuratively, spiritually and energetically. A person can figure out which items they want to keep, and which need to go. As someone who recently moved across the country, I can speak to this experience. It’s also time for what people call “the fresh start effect.” This phenomenon, according to psychologists, can happen in little moments (like the start of a new work week) and bigger moments (such as moving from one home to the next).
The fresh start effect offers these benefits often mentioned by psychologists:
- Mental Accounting: Dates act as chapter breaks, letting you put past failures into a previous period.
- Psychological Distance: You separate your flawed past self from your aspirational future self (“That was the old me”).
- Optimism Boost: New beginnings clear mental clutter and increase your sense of agency and control
Does this mean that “the new you” will be the perfect version you envisioned? Probably not. We are humans. But it might mean you get a chance to “leave some of the old you behind” within the walls you used to live in, and now have a chance to have a new layout, a new décor, a new color pattern, new wallpaper, donate old furniture and books or magazines, throw out clothes you no longer use or fit in, and enjoy the opportunity to literally use the, “Does this spark joy?” method that was made so popular by Marie Kondo in her Netflix series.
So, for all its hassle and headache, moving is a chance to shake off the “old you” and try on the new you, to incorporate the items you would like to keep and use more of, and shed the items, habits, and ways of thinking that you feel no longer serve you.
I can speak to the experiences that several of my clients had when they moved from a previous residence to a newer one. It usually coincided with a change in relationship status, a change in employment, a change in family size, but sometimes it just seemed to correlate to a new attitude and perspective that the client was really hoping for.
I have literally had clients come to me after the fact, in tears, that they were so happy they made the decision to move out of a situation that no longer served them, and move into one that felt like a much better fit.
Change can be annoying and overwhelming at times, but usually most people come out the other side, not wanting to return to the way they were before.
Joseph Hudson is a referral agent with RLAH. Reach him at 703-587-0597 or [email protected].
Real Estate
With gas prices soaring again, a staycation is a good plan
Home can be your personal retreat and your own private resort
When airfare costs more than your monthly utility bill and a weekend road trip requires a second mortgage just to fill the gas tank, many homeowners are discovering an unexpected luxury: the staycation.
A staycation isn’t settling for less—it’s reaping the benefits of one of the biggest investments you can make: your home. Much more than a place to sleep, it’s your personal retreat, your gathering place and, with a little preparation, your very own private resort.
Whether you own a single-family home, a townhouse, or a condo, creating a memorable staycation starts with appreciating what made you fall in love with your property in the first place.
Start with a home refresh. Think about checking into a beautiful vacation rental. It’s spotless, organized, and inviting. You can recreate that same feeling by spending a day preparing your home before your staycation officially begins.
Clear away clutter, deep clean the bathrooms and kitchen, wash the windows, and put fresh linens on every bed – even if you’re not expecting guests. Fluff the pillows, light a favorite candle, and place fresh flowers on the table. These small touches instantly make your home feel more luxurious.
If your budget allows, hiring a professional cleaning service can be one of the best staycation perquisites you make. After all, vacation should begin the moment you wake up and not after you’ve spent the day scrubbing floors.
Treat your staycation like a real trip. Set away messages on your phone and out of office notices on your email. Skip unnecessary chores for a few days. Giving yourself permission to relax may be the most valuable part of the entire experience.
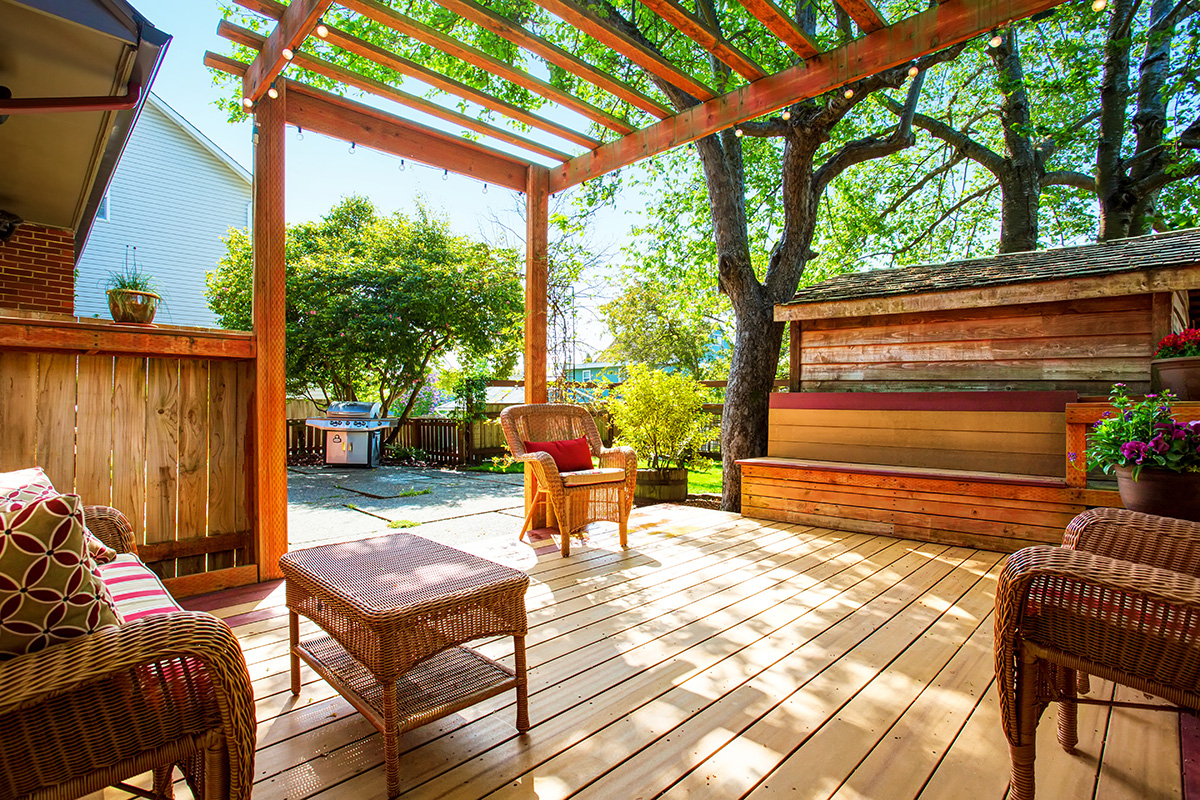
One of the greatest advantages homeowners have over travelers is private outdoor living space. Whether it’s a spacious backyard, a screened porch, a rooftop terrace, or a cozy condo balcony, these areas can become the centerpiece of your staycation.
Stringing lights and adding comfortable seating, colorful planters, and outdoor rugs can completely transform the atmosphere without spending thousands of dollars. Add a portable fire pit, a tabletop fountain, or a hammock, and suddenly your backyard starts competing with many resorts.
Host an evening cookout, organize a game night, invite neighbors over for dessert, or gather around the fire pit for conversation after sunset. These simple moments often become the memories we treasure most.
Inside, transform your family room into a home theater complete with popcorn and comfortable blankets. Turn your breakfast room into a morning coffee café. Designate a quiet reading corner where phones are prohibited. Create a spa-like bathroom with plush towels, candles, bath salts, and relaxing music.
One of the highlights of traveling is experiencing new food. Instead of dining out every night, create themed dinners inspired by your favorite destinations. Prepare homemade Italian pasta one evening, Caribbean grilled seafood another, or a backyard Texas barbecue over the weekend. For a touch of whimsy, dress the part.
Pair each meal with music and libations from the region and enjoy dinner outdoors whenever possible. Suddenly, your dining room becomes part of the vacation experience instead of just another place to eat.
Families with children can turn a staycation into an adventure by seeing their home through a child’s eyes. Set up a backyard camping experience with a tent, flashlights, and s’mores around the fire pit. Transform the living room into an indoor campground complete with sleeping bags and a movie under a blanket “fort.” Organize a backyard Olympics with relay races, water balloon tosses, scavenger hunts, or miniature golf using household items.
Encourage children to plan a family picnic in the backyard or on the patio, choose a theme for a movie marathon, or help prepare meals inspired by countries they’d like to visit someday. The goal is to create experiences your children will remember long after summer is over.
Enjoy the amenities you already pay for. Condominium communities and many planned neighborhoods offer amenities that residents often overlook.
Swimming pools, fitness centers, tennis and pickleball courts, walking trails, clubhouses, grilling stations, and community gardens are designed to enhance your lifestyle. During your staycation, make a point of exploring everything your community offers. You may discover you’ve been living beside your own private resort all along.
Real estate professionals often talk about resale value, appreciation, and return on investment. While those things certainly matter, there’s another return that’s harder to measure: the enjoyment you get from living in your home every day.
You don’t need a boarding pass to recharge. You don’t need a hotel reservation to make memories. Sometimes the perfect getaway is the one you already own.
Valerie M. Blake is a licensed Associate Broker in D.C., Maryland, and Virginia with RLAH @properties. Call or text her at 202-246-8602, email her at [email protected] or follow her on Facebook at TheRealst8ofAffairs.
Real Estate
When buying a home, it’s decisions, decisions, decisions
Keeping notes on the process makes for an informed purchase

When looking to buy a home, there are lots of details to consider. Many of my clients would come to me and say, “Joe I want to buy a place, but I haven’t decided which neighborhood to buy in.” And the struggle was real. A few clients had everything decided from the color of the hallway walls to the cabinet handles and sometimes which three square blocks they wanted to look at.
But other clients were occasionally looking at properties in areas as distinct as Union Market/NOMA, Brookland, Logan Circle, and then we would even go across the river to look at a property in Shirlington or the Van Dorn areas of Virginia, which all have their own unique flavor and characteristics.
Sometimes clients would tell me, “I only want to look in Mount Pleasant or Adams Morgan.” Or, “don’t even show me any properties west of this street or south of that street.” My job wasn’t to convince people where to live. It was to just take the parameters they set for me and find as good of a property in that zone as I could, coordinate the showings and, if necessary, offer the strategy.
One can see that buyers often had more decisions to make than a seller. From a seller’s perspective, the house was where it was, and we just had to make the best of it. But working with a buyer could mean looking at five different neighborhoods, and then being a “thought partner” to help them figure out which were the top two or three areas they had seen, and then further distilling those down into what was available and weighing those options against each other.
One house could have the dream bathroom but also be located six blocks further from a Metro stop, walkable shopping and dining, and “just too far away from my friends.” Another house could have all the neighborhood options a client was looking for, but was just not in turnkey condition, and would require an additional $30,000 of upgrades once purchased to make it into the dream home they envisioned.
One activity I often asked buyers to do was to keep an active list in their heads of the properties they liked, and to keep a running rank of the top three. I often encouraged them to bring a notebook along on the journey where they could take notes and write down questions they thought of as they looked. It was an important decision, and sometimes the largest purchase of their lives. Why not take it a little seriously, and take notes? This could often help the buyer later when they felt it was time to decide.
The point here is, keeping a notebook handy can sometimes help a person with what feels like an overwhelming process. It provides a space to explore how one feels, jot down important details to remember, and then use that to make an informed decision.
Joseph Hudson is a referral agent with RLAH. Reach him at 703-587-0597 or [email protected].

United States Conference on HIV/AIDS grapples with federal budget cuts

For lesbian victims of domestic violence, competent care is scare

UN human rights chief sounds alarm over ‘comprehensive onslaught’ against LGBTQ rights

White House press pool pushes back after Trump bars three outlets

PHOTOS: Shenandoah Valley Pride

Queer mega stars coming to D.C. this fall

Activists protest outside Turkish Embassy in D.C.

Republican challenger misgenders McBride during forum, forced to leave

A roundup of fall events not to be missed