Living
The LGBTQ generational wealth gap
Family rejection, inheritance exclusion contribute to problems
It’s no secret that LGBTQ+ people face a range of financial challenges that heterosexual people simply don’t need to contend with. Less discussed are the effects of financial discrimination on building LGBTQ+ generational wealth. The stereotypical view of a wealthy gay couple with no children and a sizable disposable income is just that — a stereotype.
In reality, the “American Dream”— buying a home, getting married, having kids, finding a good job and investing in a 401(k) — is out of reach for many LGBTQ+ people, according to a survey by TD Ameritrade. Almost two thirds (35 percent) of LGBTQ+ millennials say they are unlikely to achieve these goals by age 40, compared to fewer than half of straight millennials. The same survey found that while the average annual income for a straight household is $79,400, the average LGBTQ+ household earns just $66,200 a year.
LGBTQ+ people are being left out of generational wealth for many reasons including family rejection, systematic barriers and a lack of financial education. With almost half of LGBTQ+ adults saying they have been excluded by a family member or close friend as a result of their sexual orientation or gender identity, according to a study by the Pew Research Center, a lack of familial financial support is a common problem for many in the community.
This combination of unique financial barriers that LGBTQ+ people face is what has led to generational wealth gap. It’s a problem that will only affect more queer people if we don’t address it now.
Legacy financial exclusion
At every stage of life, it’s not uncommon for LGBTQ+ people to encounter financial challenges that their heterosexual counterparts won’t face. Being kicked out of their homes as teens due to unaccepting parents, not receiving financial support from family for college, being removed from an inheritance — the financial cost of being LGBTQ+ can be substantial.
With the average inheritance reaching close to $177,000 according to a HSBC survey and Cerulli Associates forecasting that up to $68 trillion will trickle down to younger generations within 25 years, LGBTQ+ heirs could collectively lose trillions through inheritance exclusion.
“Even much smaller amounts could help folks pay off debt, pay off a home, send their own kids to college and help them with their own retirement. Many LGBTQ+ kids aren’t getting these benefits,” explains John Auten-Schneider. Auten-Schneider is the co-owner of The Debt Free Guys blog and host of the Queer Money podcast, a leading gay money blog and podcast for the LGBTQ+ community run by him and his husband, David.
Raising a deposit for a house or apartment can be a difficult task for all people, but without financial support from family, many would not be able to fund a deposit. When David’s parents pass away, David’s sister will likely be inheriting upwards of $1,000,000. Yet, David says, he won’t receive any of this money, solely because he’s gay. “His parents have every right to do with their money what they want, but it’s a particular disappointment that they’ll do this only because he’s gay. This, of course, means we need to plan differently for our retirement than his sister does,” explains John.
Just because David and John are LGBTQ+ financial experts doesn’t mean they don’t deal with many of the same systematic challenges that impact other members of the community. Younger LGBTQ+ people also face challenges directly related to their sexuality or gender identity.
A disproportionately high number of young people experiencing homelessness identify as members of the LGBTQ+ community. According to research from the Williams Institute, between 20 percent and 45 percent of homeless youth identify as LGBTQ+. Lacking access to basic housing or financial support from family can set up a young person up for economic disadvantage before they even graduate from high school.
LGBTQ+ students also shoulder a larger student debt burden than their straight peers to the tune of an extra $16,000. “This has been attributed, in part, to LGBTQ+ college students assuming more debt simply to leave hostile home lives. In some cases, parents may forgo helping their queer children in favor of helping their straight children,” explains John.
Knowledge is power
At the start of 2020, Michigan-based Lexa VanDamme was at her financial rock bottom. Stuck at work after a 70-plus hour work week with no money in her bank account, bills due the next day and a broken down car, she decided to make a change. “I realized that I needed to face my financial situation,” says VanDamme. “I dove deep into the online world of personal finance to learn about budgeting, debt payoff methods, saving and investing.”
After her crash course in finance, VanDamme refinanced her credit card debt into a lower-rate personal loan, created a workable budget and started a side hustle to make extra income. There were a few bumps on her journey: “I actually cycled back into credit card debt three different times. I would pay it off, then eventually max it out a few months later,” says VanDamme. Still, she managed to pay off her debt by following the financial rules she had set for herself.
While trying to learn about personal finance on her own, VanDamme realized there was a need for accessible and relatable content that appealed to a wide range of people. She decided to create The Avocado Toast Budget (The ATB). Starting out as a blog just over a year ago, The ATB now counts more than 400,000 followers on Tiktok.
“For the longest time, the loudest voices in the personal finance community were cis, straight white males and, as a queer woman, I wanted to share information and tips that were often overlooked by those creators,” says VanDamme.
For many LGBTQ+ people like VanDamme, after spending so long hiding who she really was, she wanted to live as true to herself and be as free as possible. “This led to me ignoring my spending habits and being stuck in the paycheck-to-paycheck cycle. Airing my financial dirty laundry brought up similar feelings of anxiety and concern I felt when first coming out. How would people react? What would they think?” says VanDamme.
There is already a heavy stigma around talking about personal finances, especially when you may be struggling financially. “Since queer people often spend our lives fighting for the world to accept us and our queerness, we may be less apt to talk about our financial insecurities and struggles,” says VanDamme.
Genuine representation goes beyond just diversifying the financial content creators who receive media platforms, with the advice given by these experts also needing to be fully inclusive. “Advice tended to ignore how systems of oppression affect people of color, women, the LGBTQ+ community and more. We know statistically that it’s easier for some to build wealth than others,” she adds.
VanDamme has an ongoing series on Instagram focused on the intersectional nature of many financial issues. The series helps shed some light on the economic realities that often contributes to minority community challenges. From financial inequality that disproportionately impacts disabled people to wealth inequity and racism and the cycle of poverty, VanDamme works to educate her audience on pressing topics that matter to them.
“It’s especially important to talk about the financial challenges that trans people in our community face. This includes increased reports of lower wages, limited and more expensive housing options, and twice the rate of unemployment. This heavily impacts their ability to build wealth,” she explains.
Intersectional challenges
While being LGBTQ+ can underpin unique money issues, queer people of color and queer women often experience additional difficulties around financial matters.
In addition to the financial barriers faced by LGBTQ+ people, queer people of color also face a racial wealth gap. Employment discrimination, systematic inequalities and disparities in financial education all contribute to this unequal financial playing field.
According to research from the Federal Reserve, the average white family’s wealth is eight times higher than the wealth of an average Black family. The gender pay gap also contributes to excluding women from building generational wealth, according to the latest statistics compiled by Pew Research, which show that women earned 84 percent of what men earned in 2020.
Carmen Perez, creator of Make Real Cents, a personal finance blog dedicated to helping people achieve financial independence, believes it’s important to have experts who are more representative of the people they’re speaking to. “I heard a quote a while ago: ‘You can’t be what you can’t see.’ I think that’s really important because eventually, if you don’t have a model to follow, either you have to be the first, or it’s never going to happen,” she says.
As a woman of color and a lesbian, Perez knows firsthand how important it is to address the absence of representation in financial education. “It’s definitely one of the things we have to step back and look at in the LGBT community,” says Perez. “There’s a compounding effect because not only am I part of the LGBT community as a lesbian, but I’m also a minority, and I’m also a woman, and there’s a lot of hurdles up against a lot of folks in this space,” she adds.
With more than 60,000 people following her Make Real Cents account, Perez is playing a part in democratizing access to finance. There, she does everything from break down the cost of credit to explain 401(k) company matches with easy-to-read graphics and Insta stories. Her methods are a world away from the complexity of some traditional financial advisors and tools.
“Millennials are starting to change the money game because we’re delivering advice in a way that isn’t super technical. It can be so overwhelming to watch CNBC with all these screens and tickers that don’t mean anything to you personally,” says Perez.
Increased representation in the finance space means a light can be shone on vital issues, resulting in deeper conversations that make money less taboo. “We’re finding instances where historically people who have been locked out of the finance industry, by design, are speaking up. Unlike some traditional financial advisors that give out all this jargon and talk in all these terms that many may not understand,” says Perez.
Future generations
Despite the long-standing barriers facing LGBTQ+ people in gaining access to financial education and financial services, LGBTQ+ personal finance content creators now offer a way for many to improve their financial literacy in more convenient ways than ever before. While investing early and regularly is one of the most effective ways to secure a financially comfortable retirement, it’s never too late to build wealth and support for the next generation of LGBTQ+ people.
“[You can] create legacy wealth within the LGBTQ+ community by setting up your estate plan to donate to LGBTQ+ causes that will help homeless youth and [by] giving to local, younger LGBTQ+ folks you know personally,” adds John.
Negotiating the LGBTQ+ generational wealth gap is no small feat. But continuing the discussion around both financial literacy and taking steps to combat systematic financial issues can go a long way to address the financial challenges impacting the LGBTQ+ community.
“The stronger we are as LGBTQ+ individuals and allies, including our financial strength, the stronger we are as a community,” concludes John.
Finbarr Toesland is an award-winning journalist committed to illuminating vital LGBTQ+ stories and underreported issues. His journalism has been published by NBC News, BBC, Reuters, VICE, HuffPost, and The Telegraph.


Real Estate
Factors to consider when hiring an interior designer
It’s essential to have confidence in the professionals you engage
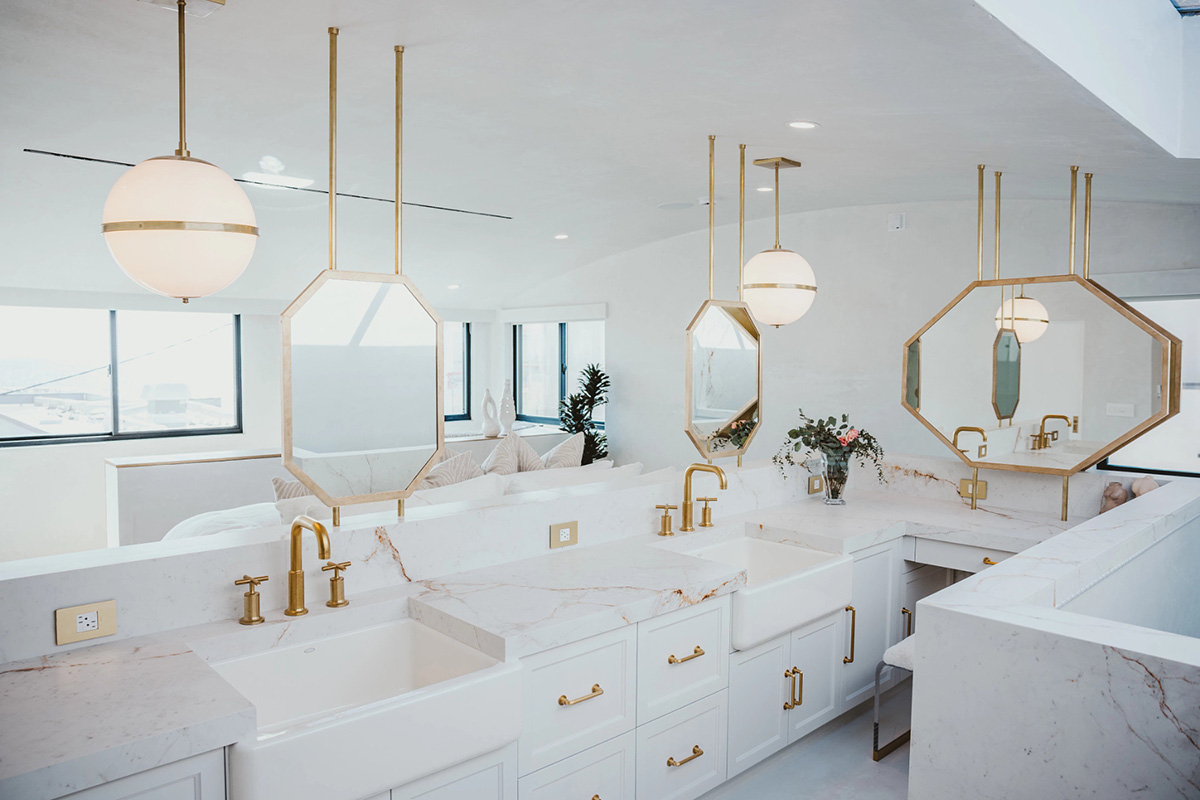
(StatePoint) Ready to redesign your home? Whether you have only a vague notion of how you want your spaces to look or a very specific vision, relying on the expertise of a professional can help you bring your dream home to life. Before choosing and hiring an interior designer, though, be sure to take the following factors into consideration:
Style: Identify your style. Is it boho chic? Industrial? Maximalist? Many designers have their own signature look and preferences. It’s best to understand what vibe you want first, then search for a designer who aligns with that style.
Past client projects: One of the best ways to know whether a particular designer is the right fit for you is to review their past client projects. Ask to see their portfolio or review their finished projects on their website or socials. Also, take a look at reviews and testimonials to ensure their previous customers walked away satisfied with a job well done.
Budget: Communicate your budget in advance of work to confirm that you and your designer are on the same page financially. Your decorator will need this ballpark figure to get a handle on the scope of the project and to make design decisions accordingly. You should also use this conversation to understand their rates so you can decide whether you want to move forward.
Preferred vendors: It’s important that the interior designer you choose has preferred vendors that they work with. These are partners they’ve built strong relationships with that provide the same first-rate experience they do, and have streamlined processes in place. “A home renovation has so many moving parts. That’s why we try to take the hassle out of the process for designers and homeowners alike,” says Katie Zess, senior marketing manager and director of Renewal by Andersen’s Interior Designer Loyalty Program.
Through the loyalty program, the full-service window and door replacement division of Andersen Corporation offers their program members exclusive access and rewards, including a “designer discount” they can share with their clients. Renewal by Andersen also offers designers a dedicated point of contact to ensure a smooth process that’s customized for your project from start to finish. To learn more, visit renewalbyandersen.com.
Before you begin your home renovation, it’s essential to have confidence in the professionals you hire. Be sure your interior designer has fostered partnerships that will streamline your redesign, and that their goals and budget aligns with yours.
Real Estate
The LGBTQ real estate map is being redrawn
Affordability, higher mortgage rates reshaping where we choose to call home
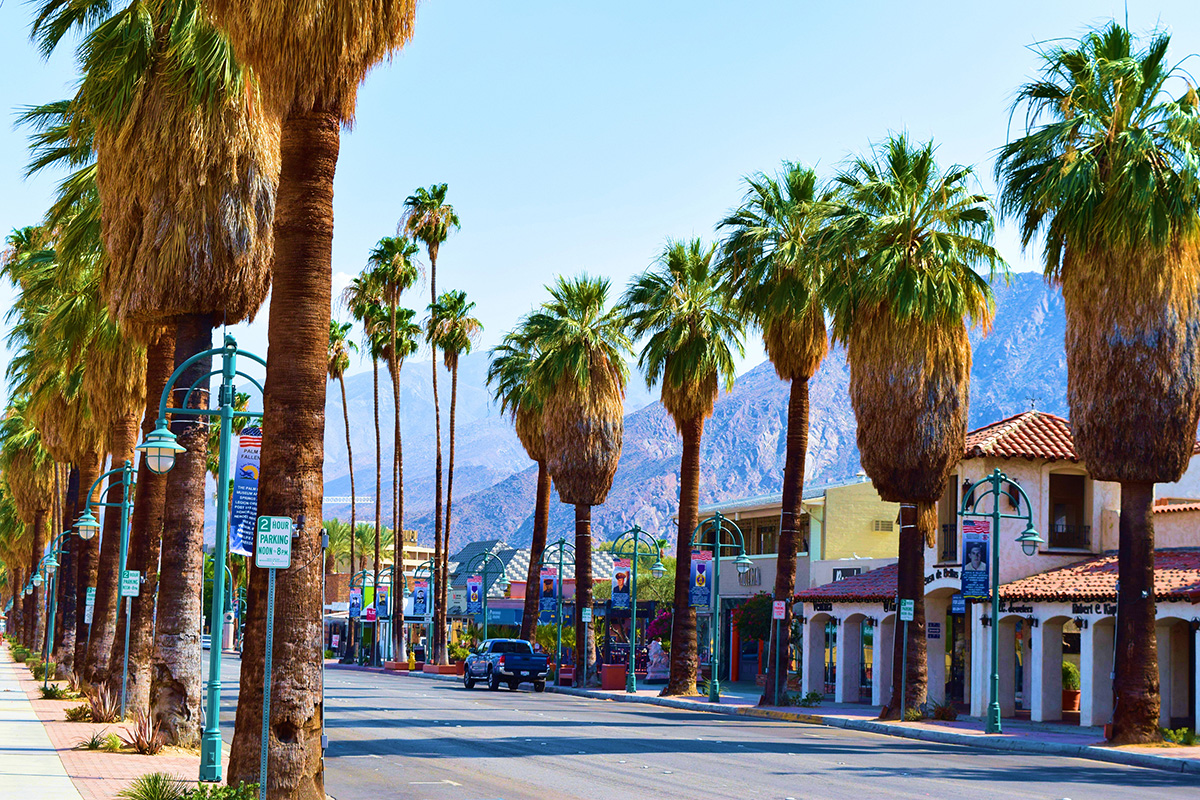
For decades, the map of LGBTQ+ America was relatively easy to recognize.
New York. San Francisco. Los Angeles. Palm Springs. Provincetown. Fort Lauderdale and Wilton Manors.
These communities became LGBTQ+ destinations because they offered something that wasn’t always easy to find elsewhere: visibility, acceptance, community and the freedom to live openly.
But that map is changing.
Today’s LGBTQ+ homebuyers are navigating a housing market defined by high prices, elevated mortgage rates and affordability challenges. At the same time, remote and hybrid work, retirement and the growth of LGBTQ+ communities beyond traditional destinations are giving buyers more choices about where to live.
Increasingly, the question isn’t simply, “Where are the most LGBTQ-friendly places to live?”
It’s also: “Where can I find community and afford the life I want?”
That shift may become one of the defining LGBTQ+ real estate trends of the coming decade.
Affordability Is Changing the Conversation
For many buyers, the biggest issue in today’s housing market is simple: the monthly payment.
The average 30-year fixed mortgage rate was 6.95% in mid-September, compared with 6.26% a year earlier, according to Freddie Mac.
Meanwhile, the median price of an existing U.S. home reached $429,100 in August, according to the National Association of Realtors.
The combination of elevated home prices and higher borrowing costs has changed what many Americans can afford—and where they can afford it.
Some buyers are purchasing smaller homes or condominiums. Others are moving farther from major urban centers. Still others are reconsidering expensive markets entirely.
For LGBTQ+ buyers, this is helping broaden the definition of an LGBTQ+-friendly place to call home.
LGBTQ+ Buyers Have More Choices
A generation ago, relocating away from a major city or established gay neighborhood could sometimes mean sacrificing access to a visible LGBTQ+ community.
That’s increasingly less true.
Traditional LGBTQ+ destinations such as Palm Springs, Fort Lauderdale and Wilton Manors, San Francisco, New York and Provincetown remain important centers of LGBTQ+ life. But today, LGBTQ+ buyers can also find established or growing communities in cities across the country.
Places such as Minneapolis, Columbus, Pittsburgh, Richmond, Atlanta and the Tampa Bay area are among the markets attracting buyers who may be looking for a different balance of housing costs, lifestyle and community.
The goal isn’t necessarily to find the cheapest house.
It’s to find the right combination of affordability, LGBTQ+ community, lifestyle, employment opportunities, healthcare, culture and quality of life.
Remote and hybrid work have expanded those possibilities for some buyers. If a job no longer requires being in an expensive employment center five days a week, the geographic search for a home can become considerably larger.
That can make communities that once seemed impractical suddenly worth considering.
Retirement Is Redrawing the Map, Too
Retirement is another important part of the changing LGBTQ+ real estate landscape.
As more Americans reach retirement age, LGBTQ+ retirees are considering where they want to spend the next chapter of their lives. Housing costs, taxes, healthcare, climate and proximity to airports, restaurants and cultural activities all play a role.
But LGBTQ+ retirees may have additional questions.
Will I feel comfortable living openly?
Is there an LGBTQ+ community nearby?
Can I find LGBTQ+-affirming healthcare?
Will I have opportunities to build a social network as I get older?
Those considerations can make choosing a retirement destination particularly personal.
Palm Springs and Fort Lauderdale/Wilton Manors remain well-known LGBTQ+ retirement destinations. But retirees are also exploring smaller cities and communities across the Southeast, Midwest and other regions where housing costs and lifestyles can look very different.
For many, the search is becoming less about moving to a famous gay destination and more about finding a place where community, lifestyle and affordability intersect.
Buyers Finally Have More Leverage
There is another significant change in today’s housing market: buyers have regained some negotiating power.
The National Association of Realtors reported 1.62 million existing homes for sale in August, up 5.9% from a year earlier. That represents approximately 4.9 months of housing supply, the highest level in more than a decade.
Realtor.com also reported that 20.4% of active listings had experienced a price reduction in August.
That’s a very different environment from the pandemic-era housing market, when buyers in many communities faced bidding wars, waived inspections and offers well above asking price.
Depending on the market, today’s buyer may have more time to evaluate a property and greater opportunity to negotiate price, repairs, closing costs or other concessions.
But there is an important caveat: there is no single national housing market.
Conditions can vary dramatically from one city—or even one neighborhood—to another. Some markets remain competitive, while others have considerably more inventory and negotiating room.
That’s one reason local expertise matters.
Sellers Need a Different Strategy
The changing market also has implications for LGBTQ+ homeowners considering selling.
Strategies that worked several years ago may not work today.
Buyers are highly sensitive to monthly payments, and an overpriced home can quickly be passed over when competing properties are available.
Sellers should pay close attention not only to recent comparable sales but also to homes currently competing for the same buyer.
Condition matters, too.
Repairs, landscaping, staging and professional photography can make a meaningful difference when buyers have more choices. Pricing correctly from the beginning has also become increasingly important.
More Than 30 Years Serving the LGBTQ+ Community
One part of buying or selling a home hasn’t changed: the importance of working with a real estate professional who understands your priorities.
For more than 30 years, GayRealEstate.com has served the LGBTQ+ community, connecting buyers and sellers with LGBTQ+ and allied real estate professionals throughout the United States.
Over that time, the GayRealEstate.com network has supported more than $2 billion in real estate sales and more than 55,000 transactions.
Behind those numbers are thousands of people making one of life’s most personal decisions: where to call home.
For LGBTQ+ buyers, that conversation can involve much more than bedrooms, bathrooms and price per square foot. It can include community, acceptance, healthcare, family, retirement, lifestyle and the ability to live openly.
An experienced LGBTQ+ or allied real estate professional can understand why those considerations belong in the real estate conversation.
Finding Home in a Changing America
The 2026 housing market presents real challenges.
Mortgage rates remain elevated. Home prices are high. Affordability continues to strain buyers across much of the country.
But there are also signs of a more balanced market. Inventory has increased. Price reductions have become more common. Buyers in many markets have regained negotiating power.
And for LGBTQ+ Americans, something else has changed: there are more places to consider calling home.
The next great LGBTQ+ destination doesn’t necessarily need the country’s largest Pride celebration or its most famous gay neighborhood.
It could be a smaller city with a growing LGBTQ+ community, attainable housing, good healthcare, strong cultural amenities and a quality of life that leaves room for travel, retirement or simply enjoying the home you’ve worked hard to own.
Ultimately, today’s LGBTQ+ real estate search increasingly comes down to three questions:
Where can I afford the life I want?
Where will I find my community?
And where will I feel at home?
The answers are becoming more varied—and that’s helping redraw the map of LGBTQ+ America.
Scott Helms is with GayRealEstate.com.
GayRealEstate.com has served the LGBTQ+ community for more than 30 years, connecting LGBTQ+ homebuyers and sellers with LGBTQ+ and allied real estate professionals across the United States. Its network has supported more than $2 billion in real estate sales and more than 55,000 transactions.
Advice
I’m 66, he’s 27. Is it love or am I being played?
What to do when your friends don’t trust your boyfriend
Dear Michael,
I’m 66, Peter is 27. I’m retired, financially comfortable. He’s a grad student.
We met last summer at the beach and started dating. Now we’re living together. I want this to be forever, and Peter says he does too.
The problem: Some of my friends are telling me that Peter is taking me for a ride.
I know all the cliches about older gay men thinking they’re in a loving relationship when the truth is they’re just some young guy’s sugar daddy. But I don’t feel old. And I think I have a grip on reality.
I do support Peter financially now, but he is eventually going to have a job. And if I didn’t pay for things, there’s no way he could share my life in terms of travel, dining out, etc. I want to have fun with him and am happy to foot the bill.
My friends say there’s no way he could be attracted to anything but my money. But I take great care of myself and look good. We don’t have the greatest sex life but I think it’s pretty hot. Peter says he is attracted to older guys.
And there’s much more to our relationship than sex. Despite the age difference, I think we are kindred spirits, and Peter says he feels the same. We both like travel, talking about politics, have similar taste in books and movies and TV shows. Lots of common interests.
I can deal with the age/money criticisms, but there’s some other stuff I’m more worried about.
One of my friends says he saw Peter making out with someone much younger over the summer. That worries me. I asked Peter about it and he said it wasn’t true.
Peter does go out, solo, because he can stay up a lot later than I want to. My party-till-dawn days are over. He says he’s just dancing and hanging out with friends. I want to believe him.
One night he didn’t come home and it unsettled me. He told me it just got too late so he crashed at a friend’s place. I thought of asking the friend about it but I didn’t want to seem like I was spying on Peter, and I also was afraid that the friend would say this didn’t happen. If it didn’t, then what? Do I break up with him for lying and cheating? I really don’t want to be old and alone. I can’t tell if my friends are making me paranoid or if I am being played.
Michael replies:
Obviously, I can’t know if Peter is telling you the truth or not. But I can give you some pointers on dealing with trust in a relationship. The main person to focus on trusting is yourself.
Do you trust your own sense of whether or not Peter is being honest with you? If not: What would it take for you to do so? Could you let yourself see things that you are currently not wanting to let yourself see? What is now stopping you from seeing him accurately?
You describe many ways in which you think the two of you are compatible. How about in terms of values? Do you respect Peter’s character? Can you get a good read on whether he is just telling you what you want to hear in order to stay in the relationship, or giving you an honest representation of where he really stands?
I understand that you’re afraid of finding out that Peter is lying to you, and that you don’t want to have to deal with ending the relationship. Given the possible ramifications, that makes sense. But do you want to let your fear stop you from keeping your eyes open?
When we decide to see things not as they are, but as we wish they were, or tell ourselves that what we see isn’t what we’re seeing, we end up getting hurt. And we do a great disservice to ourselves by discrediting our own internal witness, making it difficult to trust both ourselves and other people.
Only you can decide which would be preferable: Living with someone whom you don’t trust to be honest with you, or being alone.
In considering this possibility, keep in mind that none of us have a guarantee that we won’t be hurt in our relationships. In fact, it’s pretty much certain that at times we will be. Partners do break each other’s hearts, sometimes deliberately, sometimes not. That in itself is no reason to end a relationship.
But being with someone who is purposely deceiving you doesn’t sound that appealing.
Our relationship difficulties often give us possibilities to grow. Your fears about Peter’s infidelity are an opportunity for you two to have some conversations about how important you each think honesty is in a relationship; and what risks you are willing to take in order to have an honest relationship.
People are often afraid to speak the truth because of the possible consequences. But if you don’t speak up, you can easily wind up in a hollowed-out relationship where neither of you is willing to address what is really going on with each of you. That is the opposite of intimacy.
And, having a standard where each of you is forthcoming would avoid the minefield of a distrustful relationship where one of you is the detective and one of you is the suspect. That dynamic creates an imbalanced relationship and often leads to the watched partner wanting to get away with things.
Bottom line: Are each of you interested enough in an intimate relationship to be consistently honest with each other, even if your partner may not like what you say? And to do your best to respond thoughtfully to your partner’s honesty, even when he tells you something that you do not want to hear?
Michael Radkowsky, Psy.D. is a licensed psychologist who works with couples and individuals in D.C., Maryland, Virginia, New York, and all PSYPACT states. He can be found online at michaelradkowsky.com. All identifying information has been changed for reasons of confidentiality. Have a question? Send it to [email protected].

Trump asks Supreme Court to allow restrictions on gender-affirming care in prisons

Education Department rolls back protections for LGBTQ students under Title IX

Debbie Allen shares on loss, love, and the power of speaking out

Baltimore’s oldest gay bar to reopen this week

Dr. Fauci ‘honored to be part of’ LGBTQ history

Colombia withdraws from Equal Rights Coalition

Trump-appointed judge restores White House TV pool access

Writing a play about Lincoln leads down a rabbit hole to a closet

Philadelphia event to launch 2026 LGBT History Month

Being a female firefighter comes with unique risks, and rewards
-

 Colombia5 days ago
Colombia withdraws from Equal Rights Coalition
-
White House5 days ago
Trump-appointed judge restores White House TV pool access
-
a&e features5 days ago
Writing a play about Lincoln leads down a rabbit hole to a closet
-
National5 days ago
Philadelphia event to launch 2026 LGBT History Month